 Skip to content
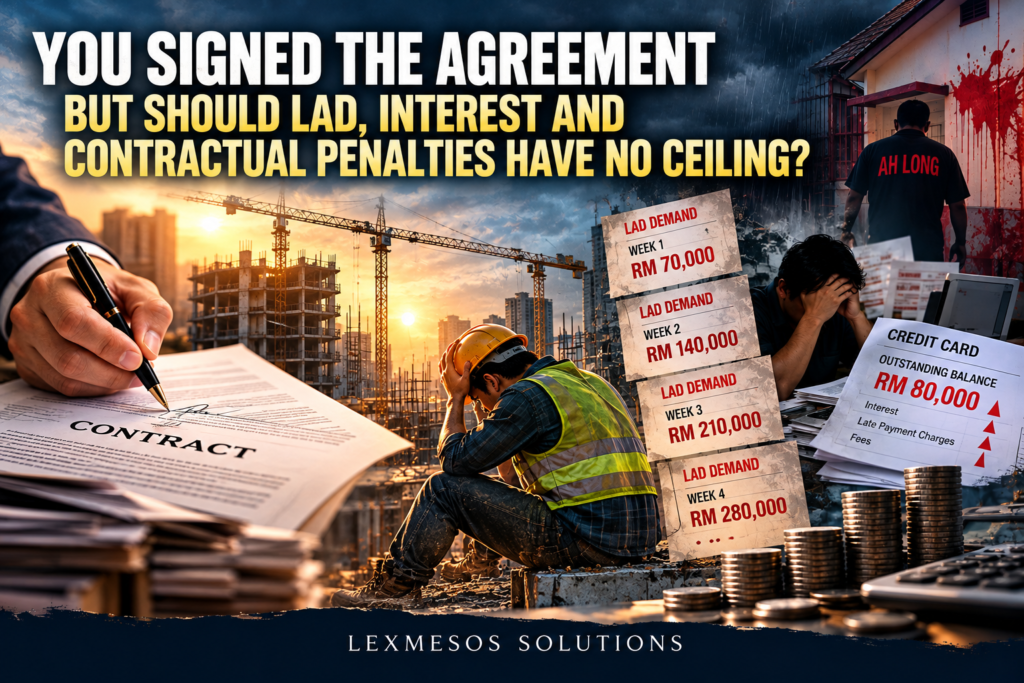
From Netflix’s Animals to Malaysian loan sharks, escalating credit-card debts and construction contracts imposing daily delay damages, the real question is whether contractual consent provides sufficient protection against disproportionate financial liability.
When a Signature Becomes an Expensive Obligation
In Animals, starring Ben Affleck, a desperate father agrees to obtain USD7 million for a ransom arrangement involving an additional 20% charge, equivalent to USD1.4 million.
When the circumstances change, he questions why the additional charge should still be payable.
The scene raises a question familiar to anyone who has signed a loan agreement, construction contract or commercial arrangement: if the original circumstances change, must every agreed financial obligation remain payable?
The answer depends on the contract and the applicable law.
A change in circumstances does not automatically discharge a contractual obligation. Nor does an agreed charge become unenforceable merely because it is expensive.
Nevertheless, a signature does not necessarily establish that every subsequent financial demand is lawful, reasonable or recoverable.
That distinction becomes especially important where one party drafts the agreement, controls the calculation of charges and has substantially greater financial resources to enforce its interpretation.
Freedom of contract should protect legitimate commercial expectations. It should not be treated as an unlimited licence to impose disproportionate financial consequences.
Malaysia’s Loan Sharks: When Borrowing Becomes Intimidation
Malaysia’s illegal moneylending problem demonstrates how financial obligations can become instruments of pressure.
A person may borrow RM10,000 and subsequently face demands for several times the original amount.
When repayment becomes impossible, the consequences may extend beyond the borrower.
Illegal moneylenders, commonly known as loan shark or “Ah Long”, have been associated with threats against family members, harassment, property damage and red paint splashed on residential properties.
These practices are not ordinary contractual enforcement.
They raise separate questions of criminal intimidation, unlawful debt collection and public safety.
Malaysia’s Moneylenders Act 1951 regulates licensed moneylending, including statutory interest restrictions. Section 15 addresses the unenforceability of agreements involving unlicensed moneylenders. (CommonLII)
The existence of a debt does not give a creditor the right to threaten relatives or damage property.
The lesson extends beyond illegal lending: a financial claim and the method used to enforce it must each have a lawful basis.
When “Agreed Profit” Is Really Interest: The Federal Court’s Warning
An important Malaysian Federal Court decision demonstrates why contractual labels should not be accepted without examining the substance of the transaction.
In Triple Zest Trading & Suppliers & 2 Ors v Applied Business Technologies Sdn Bhd [2023] 8 AMR 225, a borrower received RM800,000 under an agreement requiring repayment of an additional RM800,000 described as “agreed profit”.
The lender sought to recover RM1.6 million.
The Federal Court examined the transaction under the Moneylenders Act 1951 and concluded that the additional RM800,000 was, in substance, interest amounting to 100% of the principal.
The Court also applied the statutory presumption under Section 10OA concerning the business of moneylending.
As the lender failed to rebut that presumption and was not licensed under the Act, the loan agreement was held unenforceable under Section 15.
The Court went further, rejecting recovery of the principal through restitution in the circumstances of the case.
This decision illustrates an important principle: contracting parties cannot necessarily escape statutory restrictions merely by describing interest as profit, fees or another contractual entitlement.
It also raises a broader question relevant to contractual fairness.
If Malaysian law examines the substance of financial arrangements to prevent unlawful moneylending, should greater legislative attention also be given to the cumulative financial exposure created by certain contractual penalty and LAD provisions?
The legal frameworks are different. Ordinary loan interest, unlawful moneylending and liquidated damages for breach are not interchangeable.
Nevertheless, they raise a common policy concern: contractual wording should not be treated as a substitute for examining legality, proportionality and the protection of legitimate interests.
In construction contracts, this becomes especially relevant where daily LAD continues accumulating while disputes over delay, extensions of time and contractual responsibility remain unresolved.
The question is not whether developers should lose their right to compensation.
It is whether defined categories of construction contracts should be subject to clearer cumulative LAD ceilings and more accessible mechanisms for reviewing disputed claims.
The same principle was reinforced in Lua Thiang Poh v Kabir Singh a/l Jagir Singh & Ors [2025] MLJU 2365. The Kuala Lumpur High Court examined transactions presented as investments involving RM2.3 million in principal and approximately RM2.78 million in claimed returns. (Lexology)
Despite being documented through promissory notes, the arrangements were found to constitute unlicensed moneylending rather than genuine investments. Applying the Moneylenders Act 1951 and the Federal Court’s reasoning in Triple Zest, the High Court dismissed the claim. The decision reinforces a fundamental distinction: the label chosen by contracting parties does not determine whether a financial arrangement is lawful or enforceable.
Credit-Card Debt: When RM20,000 Becomes RM80,000
Consider an anonymised account of a Malaysian credit-card borrower whose outstanding balance was reportedly approximately RM20,000.
Over several years, the amount demanded allegedly increased to RM80,000.
The borrower reportedly attempted to negotiate a settlement, but the proposal was rejected. No further payments were made and the person later passed away.
This account has not been independently verified and does not establish misconduct by any particular financial institution.
However, it illustrates a legitimate concern about the cumulative effect of interest and default.
Malaysian credit-card finance charges are regulated, with commonly applicable annual rates of 15%, 17% and 18%, depending on repayment behaviour.
But a regulated annual rate is not necessarily a ceiling on the total interest that can accumulate over a prolonged period.
A borrower who cannot settle the outstanding balance may face continued charges, subject to the contractual terms and applicable regulatory requirements.
The result can be a debt that becomes increasingly difficult to repay.
There are also important legal distinctions.
Under Section 6(1)(a) of the Limitation Act 1953, contractual claims in Peninsular Malaysia are generally subject to a six-year limitation period from accrual of the cause of action.
The applicable date may be affected by the contractual terms, qualifying acknowledgment, part payment or earlier proceedings.
A bank does not automatically extend the limitation period simply by issuing another demand letter or continuing to calculate interest.
However, limitation generally operates as a defence to court proceedings rather than automatically extinguishing the debt.
Should consumer-credit regulation focus only on the annual rate charged, or should it also examine the total financial burden that may accumulate during prolonged default?
That is a policy question deserving closer examination.
Construction LAD: The Financial Clock That Keeps Running
The problem becomes especially significant in construction contracts.
A developer appoints a contractor to complete a project by an agreed date. The contract specifies liquidated ascertained damages (LAD) for late completion.
Once the contractual completion date passes, the developer begins issuing letters calculating the daily LAD allegedly payable.
One week passes. Another letter arrives.
Another week passes. The accumulated amount increases.
The contractor is still on site, paying workers, purchasing materials, dealing with subcontractors and trying to complete the project.
Yet the claimed liability continues growing.
Consider a hypothetical RM5 million construction contract containing LAD of RM10,000 per day.
| Alleged delay | Accumulated LAD |
|---|---|
| 7 days | RM70,000 |
| 30 days | RM300,000 |
| 60 days | RM600,000 |
| 90 days | RM900,000 |
| 180 days | RM1,800,000 |
After six months, the calculated LAD reaches RM1.8 million, equivalent to 36% of the original contract value.
These figures illustrate the mathematical effect of an uncapped daily rate. They do not mean that the entire amount would necessarily be enforceable.
The developer may have legitimate reasons for requiring timely completion.
Delay can result in financing costs, lost revenue, disruption to purchasers, operational difficulties and other commercial consequences.
But the contractor’s position also matters.
What if the developer changed the design repeatedly?
What if site access was delayed?
What if drawings or approvals were issued late?
What if the contractor requested an extension of time, but the application remained unresolved?
What if the developer’s own conduct contributed to the delay?
A daily LAD clause does not eliminate these questions.
The applicable completion date, extension-of-time provisions, responsibility for delay, contractual notices and other relevant conditions must still be examined.
A weekly letter stating that LAD has accumulated is not, by itself, a court determination that the contractor owes that amount.
The central concern is not whether developers should be compensated for delay. It is whether the contract should allow financial exposure to continue accumulating without a clear overall limit.
What Malaysian Courts Have Actually Decided
Section 75 of the Contracts Act 1950 governs reasonable compensation where a contract specifies a sum payable upon breach or contains a stipulation by way of penalty.
The Federal Court’s decision in Cubic Electronics Sdn Bhd (in liquidation) v Mars Telecommunications Sdn Bhd [2019] 6 MLJ 15 significantly clarified the application of that provision.
The decision moved away from an approach that generally required proof of actual loss where the loss was capable of assessment.
Under Cubic Electronics, proof of actual loss is not invariably necessary to enforce a stipulated damages clause.
The party seeking compensation must initially establish the relevant breach and the contractual provision specifying the amount payable.
Once those requirements are satisfied, the defaulting party bears the burden of demonstrating why the stipulated compensation is unreasonable.
The court may consider legitimate commercial interests, proportionality and evidence of actual loss when assessing reasonable compensation.
This development promotes contractual certainty.
A party that negotiated a damages provision should not necessarily have to prove every element of financial loss before the clause can have legal effect.
That principle is understandable, particularly in commercial transactions where losses may be difficult to calculate precisely.
But it also creates a practical concern.
When Reasonableness Becomes the Weaker Party’s Burden
Imagine a smaller contractor receiving weekly LAD demands from a developer with considerably greater financial resources.
The developer may have drafted the contract, appointed consultants, controlled payment certification and reserved broad contractual powers over certain decisions.
The contractor may already be experiencing cash-flow difficulties.
If the developer establishes the contractual basis for LAD, the contractor may then have to demonstrate that the stipulated amount is unreasonable.
That could require legal representation, delay analysis, expert evidence and prolonged proceedings.
The law provides a mechanism to challenge unreasonable compensation.
But the existence of a legal defence does not necessarily mean the financially weaker party can afford to exercise it.
This is the distinction that deserves greater attention.
The question is not whether Cubic Electronics should be disregarded.
It is whether the current framework provides sufficient practical protection where one contracting party has substantially greater bargaining power and resources.
The Problem With “Sole and Absolute Discretion”
Many commercial contracts contain provisions granting one party broad discretion.
For example, an agreement may state that the employer has sole discretion to waive LAD, determine certain charges or approve extensions of time.
Such provisions may serve legitimate commercial purposes.
But where one party drafts the contract and the other has little meaningful opportunity to negotiate, broad discretionary powers can create an imbalance.
A smaller contractor may face a difficult choice: accept the developer’s standard terms or lose the project.
Signing the agreement does not necessarily mean both parties negotiated on equal terms.
Nor does the phrase “sole and absolute discretion” automatically make every decision immune from legal scrutiny.
The scope of the discretion depends on the contract, applicable legal principles and any relevant statutory requirements.
Importantly, a contractual power to assess LAD does not automatically override Section 75’s requirement of reasonable compensation.
The broader concern is whether contractual discretion should be accompanied by clearer duties of transparency, objective assessment and accessible review.
If one party drafts the penalty, calculates the amount, controls the relevant certification process and decides whether to waive the charge, what safeguards protect the other party?
What Other Countries Can Teach Malaysia
Malaysia is not alone in confronting the tension between contractual certainty and disproportionate financial consequences.
Different jurisdictions have developed different methods of controlling stipulated damages and penalties.
United Kingdom: Legitimate Interests and Proportionality
In Cavendish Square Holding BV v Makdessi [2015] UKSC 67, the UK Supreme Court considered whether a contractual detriment imposed for breach was out of all proportion to the innocent party’s legitimate interest in performance.
The approach recognises that an enforceable clause need not always reflect a precise pre-estimate of financial loss.
But it also rejects the proposition that every agreed penalty must automatically be enforced.
Australia: Contractual Penalties and Banking Charges
Australian decisions have influenced the development of Malaysian penalty jurisprudence.
In Paciocco v Australia and New Zealand Banking Group Ltd [2016] HCA 28, the High Court considered credit-card late-payment fees.
The majority upheld the challenged fees, recognising that the bank’s legitimate interests were not necessarily confined to the immediate administrative costs of late payment.
The decision demonstrates that a fee exceeding direct processing costs is not automatically unlawful.
It also illustrates the limits of relying exclusively on judicial proportionality analysis to protect consumers.
Singapore: A More Traditional Approach
In Denka Advantech Pte Ltd v Seraya Energy Pte Ltd [2020] SGCA 119, Singapore’s Court of Appeal retained the traditional genuine pre-estimate of loss approach rather than adopting the broader UK legitimate-interest test.
Singapore therefore provides an important comparison because jurisdictions sharing common-law traditions do not necessarily adopt identical tests.
India: Reasonable Compensation
Section 74 of the Indian Contract Act 1872 provides for reasonable compensation not exceeding the stipulated amount.
Indian jurisprudence illustrates another statutory approach to preventing contractual amounts from becoming automatically recoverable simply because they appear in an agreement.
France: Express Judicial Adjustment
Article 1231-5 of the French Civil Code permits courts to reduce contractual penalties that are manifestly excessive and increase those that are manifestly too low.
This provides an express statutory mechanism for judicial adjustment.
Germany: Reduction of Excessive Penalties
Section 343 of the German Civil Code (Bürgerliches Gesetzbuch – BGB) permits judicial reduction of disproportionately high contractual penalties.
However, important commercial-law restrictions apply, including under Section 348 of the German Commercial Code (Handelsgesetzbuch – HGB).
These international approaches do not establish a universal numerical LAD ceiling.
They demonstrate that different legal systems seek to reconcile contractual freedom with limits on disproportionate compensation.
Should Malaysia Introduce a Cumulative LAD Ceiling?
Malaysia’s current Section 75 framework already restricts recovery to reasonable compensation not exceeding the amount stipulated under the relevant contractual provision.
But that is not equivalent to a universal statutory cap expressed as a percentage of contract value.
Where LAD is calculated daily and the contract contains no aggregate ceiling, the claimed amount may continue increasing with the period of delay.
The absence of a fixed cumulative ceiling can create significant uncertainty for contractors.
That uncertainty may be particularly damaging to smaller businesses operating on limited margins.
Malaysia should therefore consider whether defined categories of construction and standard-form commercial contracts would benefit from clearer statutory safeguards.
Possible reforms include:
1. A cumulative LAD ceiling
Require contracts within specified categories to state a maximum aggregate LAD exposure, potentially expressed as a percentage of the contract value.
The appropriate ceiling should be determined through consultation with industry participants and consideration of project risks.
2. Transparent calculation methods
Require LAD provisions to clearly identify the daily rate, method of calculation, maximum exposure and circumstances in which the charge may arise.
3. Fair assessment of extensions of time
Strengthen procedural safeguards for contractors seeking extensions where delays arise from employer instructions, variations, late approvals or other contractually recognised events.
4. Independent review of disputed assessments
Provide affordable mechanisms for reviewing disputed LAD calculations without requiring every disagreement to become prolonged litigation or arbitration.
5. Scrutiny of unilateral contractual discretion
Encourage objective criteria and transparent decision-making where one party controls assessments affecting the other’s financial liability.
6. Proportionate protection for smaller contractors
Consider targeted safeguards for small and medium-sized businesses entering standard-form construction contracts with substantially stronger counterparties.
These proposals require careful design.
A universal cap that is too low could undercompensate developers facing serious delay-related losses.
A poorly designed cap could also encourage strategic non-performance.
Any reform must therefore preserve legitimate contractual remedies while reducing the risk of disproportionate exposure.
Should Interest and LAD Be Treated the Same Way?
No.
Ordinary loan interest compensates a lender for providing credit.
Default charges may arise from non-payment or other contractual events.
LAD generally concerns stipulated compensation for breach.
Illegal moneylending and criminal intimidation raise additional statutory and criminal-law issues.
These obligations are not legally interchangeable.
However, they share a policy concern: financial liabilities can become increasingly burdensome where the contractual terms are complex, bargaining power is unequal or the total exposure is difficult to predict.
A meaningful reform agenda should therefore distinguish the applicable legal rules while asking whether the existing safeguards are sufficient.
For consumer credit, the question may concern total recoverable interest, hardship restructuring and transparent debt calculations.
For construction LAD, the question may concern cumulative ceilings, fair delay assessment and access to affordable dispute resolution.
For illegal moneylending, the priorities include enforcement against unlawful lending and protection from harassment and intimidation.
Different problems require different legal responses.
The Cost of Enforcing Fairness
A recurring weakness in contractual protection is the assumption that a party can simply go to court.
In principle, a borrower can dispute an unlawful charge.
A contractor can challenge an unreasonable LAD clause.
A business can contest a contractual interpretation.
But legal proceedings cost money.
A financially stronger party may be able to sustain a dispute for years.
A smaller business may struggle to fund expert reports, legal representation and ongoing operations simultaneously.
This does not mean the stronger party is necessarily wrong.
It means that access to legal remedies should form part of any serious discussion about contractual fairness.
A right that is prohibitively expensive to exercise may offer limited practical protection.
Conclusion: A Signature Should Not End the Discussion
Contracts are essential to commercial certainty.
Lenders must be able to recover lawful debts. Developers must be able to protect themselves against genuine delay. Contractors must honour their performance obligations.
But contractual certainty should not be confused with unlimited financial liability.
Malaysia’s Cubic Electronics decision provides an important framework for enforcing stipulated damages while preserving the requirement of reasonable compensation.
The remaining policy question is whether judicial scrutiny alone provides sufficient protection against the cumulative effect of high LAD rates, unequal bargaining power and costly disputes.
The same broader concern arises when consumer debts grow over many years or borrowers face financial demands they cannot meaningfully challenge.
The law should not merely ask whether a party signed the agreement. It should also examine whether the financial consequences are proportionate, transparent and subject to effective legal safeguards.
Malaysia should consider targeted cumulative LAD ceilings, clearer disclosure of contractual exposure and more accessible mechanisms for resolving disputes.
Such reforms would not undermine contractual responsibility.
They could help ensure that contractual responsibility remains commercially predictable and legally proportionate.
Because a contract should allocate risk, not create financial exposure without meaningful limits or scrutiny.
Keywords: Liquidated ascertained damages (LAD) in Malaysia, Section 75 Contracts Act 1950, LAD ceiling in construction contracts, excessive daily LAD charges, cumulative LAD limits, construction project delays, extension of time (EOT) disputes, developer and contractor contractual disputes, unequal bargaining power in commercial agreements, unfair contract terms in Malaysia, contractual penalties and reasonable compensation, Cubic Electronics Federal Court decision, enforceability of liquidated damages clauses, excessive loan interest and credit-card debt, illegal moneylenders and Ah Long in Malaysia, limitation period for debt recovery, contractual discretion and financial liability, proportionality of contractual damages, international comparison of penalty clauses, construction contract risk management, statutory reform of LAD in Malaysia, protection of small contractors and SMEs, and fair contractual enforcement
This article is provided for general information and legal-policy discussion. It does not constitute legal advice. Contractual enforceability depends on the applicable law, the agreement’s terms and the circumstances of each case.
13 October 2026