 Skip to content
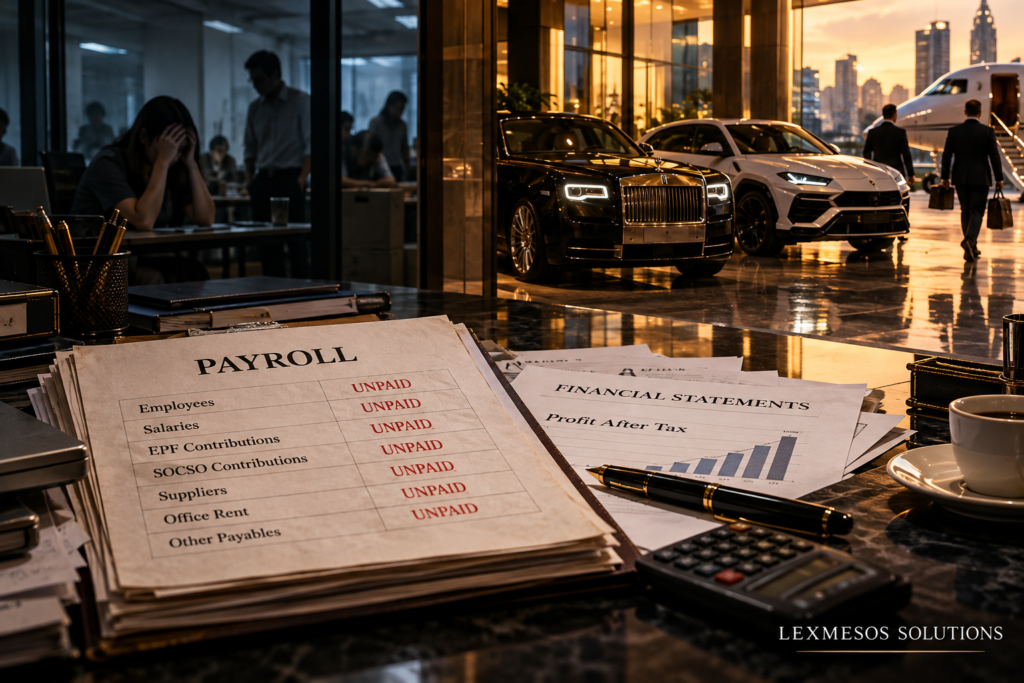
When a publicly listed company reports profits but cannot pay its employees, suppliers or rent, the uncomfortable questions extend well beyond its bank balance.
Imagine a company announces another profitable year. Investors are reassured, business continues and the directors appear to be enjoying the rewards of success.
Yet behind the respectable financial statements, employees may be waiting months for their salaries. Suppliers are chasing invoices. The landlord has not received rent. Statutory contributions remain outstanding.
Management’s explanation is familiar: the company has no money.
No money for whom, exactly?
It is difficult to reconcile claims of financial hardship with the sight of senior executives driving luxury cars, travelling extravagantly and continuing to enjoy a lifestyle that appears untouched by the company’s financial difficulties.
Of course, there is nothing inherently unlawful about a director owning a Bentley, Rolls-Royce or Lamborghini. Successful businesspeople may have accumulated substantial personal wealth independently of their companies. The law does not require directors to live modestly simply because their businesses are struggling.
But what happens when the money funding that lifestyle may have come from the company itself? What if corporate funds are transferred to businesses controlled by directors, while employees and creditors are repeatedly told to wait?
That is where an ordinary cash-flow problem may become a question of corporate governance, fiduciary duties and potentially serious legal misconduct.
A profitable company can still run out of cash
One misconception deserves to be addressed immediately. A company reporting profits is not necessarily a company with money available to pay its bills.
Accounting profits and cash flow are different things. Revenue may be recognised before customers pay. A company may hold valuable assets that cannot readily be converted into cash. It may also have substantial financing commitments, overdue receivables or other liabilities.
A profitable company can therefore experience genuine liquidity problems without falsifying its accounts.
However, there is a considerable difference between experiencing financial difficulties and deliberately creating a misleading impression of financial strength.
Imagine a listed company receiving a substantial injection of money shortly before its financial year-end. The money appears in its bank account when the financial statements are prepared. Shortly afterwards, it is withdrawn or returned.
Is that illegal?
Not necessarily. A genuine short-term loan, properly recorded and disclosed, may be entirely legitimate. The injection itself would not ordinarily constitute profit.
But suppose the transaction was deliberately structured to disguise the company’s actual liquidity, conceal related-party dealings or mislead investors about its financial position. The legal implications could be very different.
The timing of the transfers, their commercial purpose, accounting classification, subsequent repayment and disclosure would all require examination.
An auditor should not merely be satisfied that money appeared in the bank account on a particular date. The underlying substance of material transactions matters just as much as their documentary appearance.
When directors have businesses of their own
It is perfectly lawful for directors to own other companies, subject to their legal duties and applicable restrictions.
The difficulty arises when their personal business interests begin to overlap with the interests of the company they are supposed to serve.
Suppose a director-controlled business receives consultancy fees, management charges, advances or other payments from a listed company that is struggling to meet its obligations.
There may be legitimate commercial explanations. The services might have been genuinely provided, the charges reasonable and the transactions properly authorised.
But what if no meaningful services were delivered? What if payments were made principally to benefit the directors? What if the transactions were concealed from shareholders or improperly recorded?
Under Section 213 of Malaysia’s Companies Act 2016, directors must exercise their powers for proper purposes, in good faith and in the company’s best interests. They must also exercise reasonable care, skill and diligence.
Section 218 addresses the improper use of company property, information, position and opportunities to obtain benefits or cause detriment to the company, subject to the statutory requirements concerning consent or ratification.
These obligations are not suspended because a director founded the company, owns a substantial number of shares or enjoys the confidence of overseas investors.
A company is a separate legal entity. Its money is not the personal wallet of those controlling it.
For listed companies, transactions involving directors and connected parties may also engage Bursa Malaysia’s related-party transaction requirements. Depending on their nature and size, disclosure, audit committee consideration, shareholder approval or other safeguards may be required.
A payment does not become legitimate simply because it has been labelled a consultancy fee or approved by someone within management.
The underlying transaction must withstand scrutiny.
When the auditor is too close to management
An external auditor is appointed to provide independent assurance concerning financial statements, not to help management create a more attractive picture for investors.
Professional familiarity with a client is unavoidable. Auditors communicate regularly with directors and finance personnel. They may develop longstanding working relationships.
But friendship, financial dependence or excessive familiarity can create threats to professional independence.
The concern becomes more serious where an auditor allegedly advises management on transactions designed to improve financial figures temporarily around reporting dates.
There is an important distinction between legitimate accounting advice and participation in misleading financial reporting. An auditor may properly advise a company on accounting standards, disclosures and the treatment of genuine financing arrangements.
Knowingly helping management conceal the economic substance of transactions is another matter.
Malaysia’s Capital Markets and Services Act 2007 imposes specific obligations concerning listed corporations. Section 319 addresses accounting records and financial reporting, while Section 320 sets out circumstances in which auditors must report specified breaches or materially adverse financial matters to the relevant authorities.
The Securities Commission’s Audit Oversight Board oversees auditors of public-interest entities, including listed companies.
If an auditor knowingly facilitates misleading reporting, the consequences may extend beyond professional embarrassment. Depending on the evidence, disciplinary, regulatory and criminal questions may arise.
The public should not have to wonder whether an audit opinion reflects independent professional judgment or the preferences of the people paying the audit fees.
Listed companies face another layer of accountability
The Companies Act 2016 already imposes serious consequences for knowingly false or misleading corporate reporting.
Section 591 addresses materially false or misleading statements in documents, including financial statements, where the relevant knowledge or intention requirements are satisfied. A corporation may face a fine of up to RM3 million. Responsible officers and other individuals falling within the provision may face imprisonment of up to ten years, a fine of up to RM3 million, or both.
Section 592 separately addresses certain false or misleading reports furnished by corporate officers with intent to deceive.
For listed companies, Section 369 of the Capital Markets and Services Act 2007 may also apply to specified false or misleading statements or reports concerning the affairs of listed corporations. Conviction can carry imprisonment of up to ten years, a fine of up to RM3 million, or both.
Being publicly listed does not automatically increase every penalty. Rather, listing introduces additional securities-law and disclosure obligations, creating further potential avenues of liability.
Bursa Malaysia may also take enforcement action for breaches of its Listing Requirements.
What matters is not simply whether a financial statement contains an error. Investigators must establish the relevant statutory elements, including materiality, knowledge, intention or other requirements applicable to the alleged offence.
Poor accounting, aggressive accounting judgments and deliberate falsification are not interchangeable descriptions.
And what about the overseas investors?
Some businesses become heavily dependent on continued investment rather than cash generated from sustainable operations.
That is not necessarily improper. Many companies require external capital to finance expansion, research, acquisitions or periods of commercial difficulty.
But investors are entitled to accurate information about the financial position and affairs of the businesses in which they invest, in accordance with applicable law.
A company repeatedly seeking fresh funding while struggling to meet existing obligations raises legitimate questions about how previous funding was used, whether material risks were disclosed and whether the business has a credible financial plan.
If funds are diverted to director-controlled entities or personal expenditure without legitimate authorisation, the issue becomes considerably more serious.
It would be wrong to assume that every investor-funded company experiencing financial difficulties is operating fraudulently. Equally, continued investment should not be mistaken for proof that a company is financially healthy.
A business can remain operational for some time while its underlying financial position deteriorates.
Employees are not voluntary financiers of the business
Perhaps the most troubling aspect of corporate financial distress is the position of employees.
Investors accept commercial risk in exchange for the possibility of financial returns. Suppliers negotiate payment terms and may assess credit exposure before supplying goods or services.
Employees, however, have already provided their labour.
When wages remain unpaid for months, workers are effectively being forced to finance the company’s operations through their own unpaid earnings.
Under Section 19 of Malaysia’s Employment Act 1955, wages must generally be paid no later than the seventh day after the end of the relevant wage period, subject to statutory exceptions.
A company’s financial difficulties do not automatically excuse non-payment.
Employees may pursue qualifying salary and contractual payment claims through the Labour Court administered by the Department of Labour, commonly known as JTK.
Unpaid EPF and SOCSO contributions involve separate statutory obligations and enforcement mechanisms.
Where prolonged non-payment leads an employee to resign, constructive dismissal may also arise, depending on whether the employer’s conduct amounts to a fundamental breach and whether the employee responds in a manner consistent with that breach. Such claims follow the separate industrial relations process.
But obtaining a favourable decision is only part of the struggle.
An employee may succeed in establishing five months of unpaid salary, only to discover that the employer has insufficient readily recoverable assets to satisfy the order.
Meanwhile, directors may continue receiving remuneration, operating other businesses or enjoying personal wealth that is legally separate from the company’s assets.
That disparity is understandably difficult for employees to accept.
It also exposes an important limitation in corporate accountability: punishment and compensation are not the same thing.
A regulatory fine does not automatically repay an employee’s salary. An auditor’s suspension does not settle an unpaid supplier’s invoice. Even the successful prosecution of a director may leave creditors facing lengthy recovery proceedings.
Where a company becomes insolvent, statutory priorities and insolvency procedures introduce further complications.
The legal system provides remedies, but the availability of a remedy does not guarantee that money will ultimately be recovered.
When financial distress becomes a governance failure
In my view, the most revealing question is not whether a director owns an expensive car or takes luxurious holidays.
It is whether the company’s decision-makers can properly account for the money entrusted to them.
Were payments to related businesses commercially justified? Were conflicts of interest disclosed? Did the board exercise meaningful oversight? Were auditors genuinely independent? Did the financial statements fairly represent the company’s position? Were employees’ statutory entitlements respected?
These are questions of governance, not personal lifestyle.
A director’s private wealth should not become the subject of suspicion merely because a company experiences financial difficulty. But corporate resources must not be treated as personal property, particularly when the company is unable to honour its obligations.
Financial distress can happen to any business. Markets change, customers default, projects fail and unexpected costs arise. Even responsibly managed companies can encounter serious difficulties.
What separates financial misfortune from potential misconduct is how those responsible behave, what they disclose and whether they continue acting in accordance with their legal duties.
There is also a danger in treating an auditor’s signature as an absolute guarantee. An audit provides reasonable assurance, not certainty. Independent scrutiny remains essential, especially where complex transactions, related parties and liquidity concerns intersect.
Ultimately, the credibility of a listed company depends on more than the profits appearing in its annual report.
It depends on whether those figures can withstand scrutiny, whether the directors can explain their decisions and whether the company’s obligations are being taken seriously.
A business should not be judged solely by the cars parked outside its directors’ homes.
But neither should employees be expected to accept endless explanations about financial hardship while legitimate questions concerning corporate expenditure remain unanswered.
When a company says there is no money, asking where the money went is not an unreasonable question.
It may be the most important question of all.
Keywords: Corporate governance in Malaysia, unpaid employee salaries, financial statement manipulation, directors’ fiduciary duties, misuse of company funds, publicly listed company misconduct, auditor independence, related-party transactions, Bursa Malaysia compliance, and corporate financial accountability
Disclaimer: This article is an independent legal and corporate governance commentary by LexMesos Solutions. It discusses general legal principles and hypothetical circumstances, without making findings of misconduct against any identified company or individual. It does not constitute legal advice or an allegation that any particular person has committed an offence.
29 October 3026